- Published 2026.10.28 17:35
SK hynix and parent rating outlooks raised
Long-term contracts and 98 trillion won net cash praised
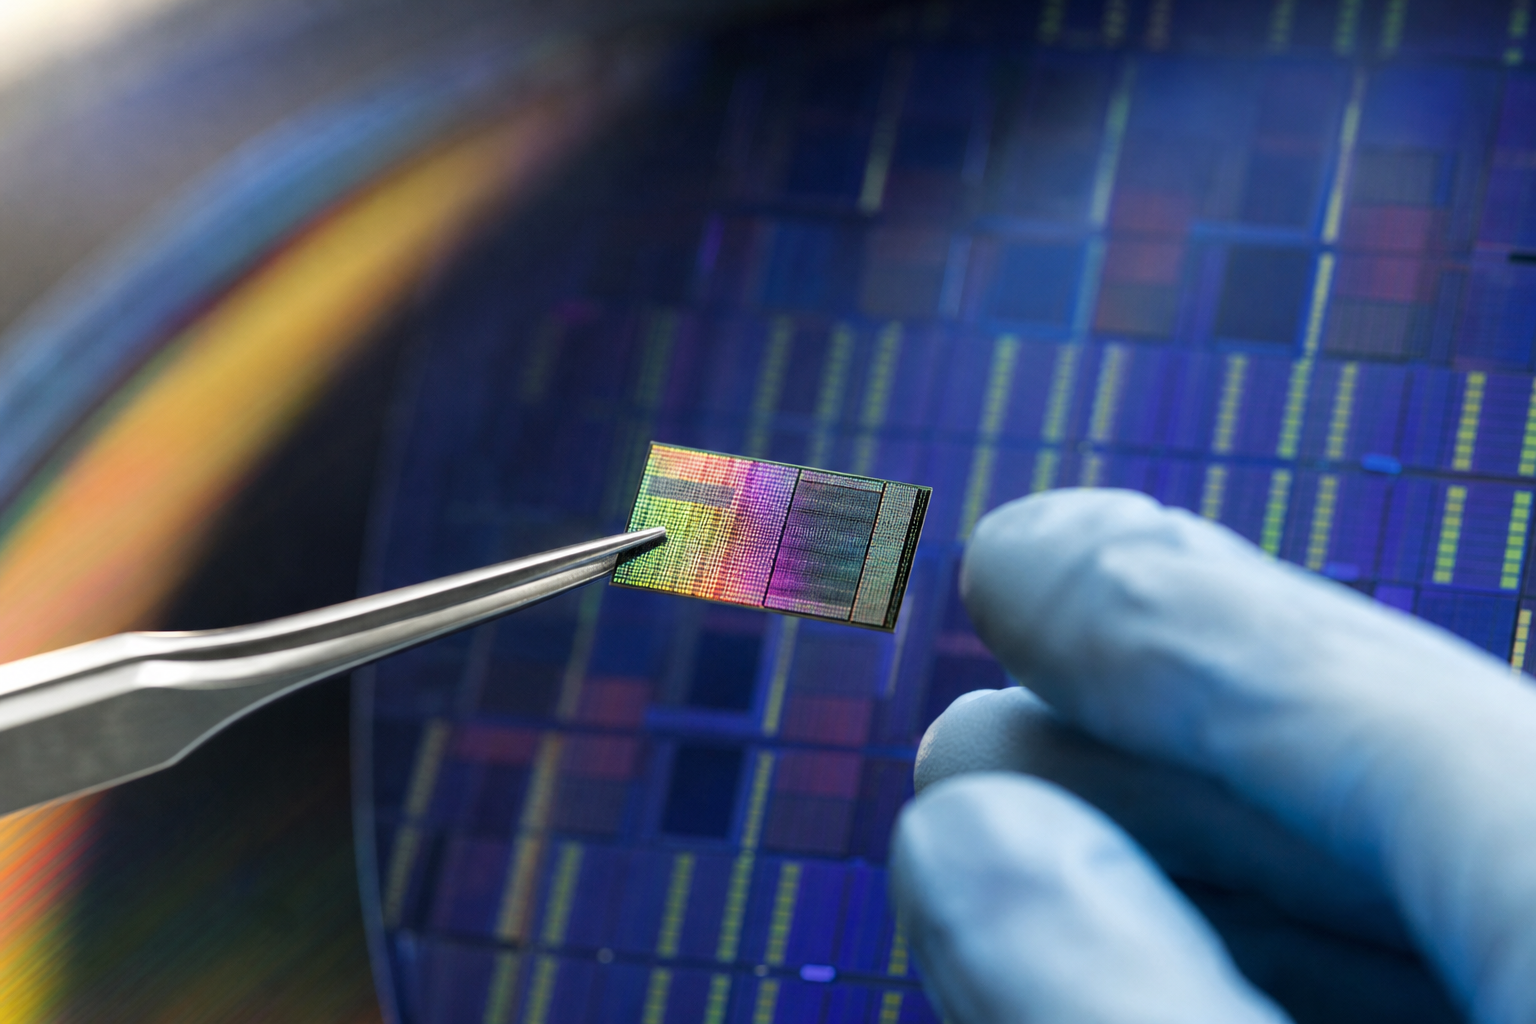
Korea Investors Service on Oct. 28 raised its rating outlook on SK hynix and its parent SK Square to positive from stable. The two companies' credit ratings were kept at AA+. In the credit rating industry, a positive outlook means the rating could be raised to the top AAA level depending on future earnings and financial conditions.
With the upgrade, SK hynix is seen as having partly eased concerns about industry cyclicality, a chronic weakness of the memory chip sector, as it enters a period of structural growth in artificial intelligence (AI) memory demand.
The key driver of the upgrade is solid earnings power led by high bandwidth memory (HBM). SK hynix is leading the global HBM market. HBM requires memory makers to participate from the early stages of customer product development and undergo long performance certification. This makes it difficult to switch suppliers or expand volume in the short term. As a result, advance volume discussions and long-term supply contracts have increased, improving demand and price visibility and serving as a buffer in downturns.
Overwhelming financial buffers also supported the positive assessment. According to Korea Investors Service, based on preliminary results as of end-September, SK hynix's total debt to EBITDA was about 0.1 times, indicating a very low debt burden relative to cash generation. Net cash reached 98.7 trillion won (about $73 billion). The company maintains a conservative financial policy of keeping capital expenditure within the mid-30% range of revenue, so net cash is expected to grow further by 2027 despite large investment plans.
The improved financial health of the key subsidiary directly led to a higher credit rating for the holding company SK Square. SK Square depends on SK hynix for most of its revenue and assets within the group. As the subsidiary's rating outlook turned positive, the possibility of an upgrade in SK Square's consolidated credit rating increased. Reduced concerns about deepening structural subordination of holding company debt, based on ample liquidity, also worked favorably.
However, there are clear hurdles to overcome before this boom translates into a top credit rating. The biggest risk is whether big tech companies leading AI infrastructure investment can actually monetize their investments. If AI models and services that have absorbed astronomical capital fail to generate profits and investment is delayed, the long-term growth trend in memory demand itself could be shaken.
In addition, the impact of additional investment burdens from U.S. government demands to expand local production and pressure from Chinese memory makers rapidly improving their technology on SK hynix's market position will be key indicators determining the future credit rating.
(Dollar figures are approximate, converted automatically at 1,000 won = $0.738, the rate on Nov. 9, 2026.)
※ This article is an AI translation of the Korean original published by Korea Credit News; it was checked by automated quality guards and published by the English edition desk.