- Published 2026.11.09 16:52
Long-term rating raised to A+, net debt metrics improve sharply
Engine unit added, cumulative operating margin hits 8.7% in first three quarters
Ability to sustain capex amid high rates remains key
NICE Credit Rating said on Nov. 9 it upgraded HD Construction Equipment's long-term credit rating to A+ from A and newly assigned a short-term rating of A2+. The upgrade reflects the financial results of the business restructuring completed in January through the merger with HD Hyundai Infracore.
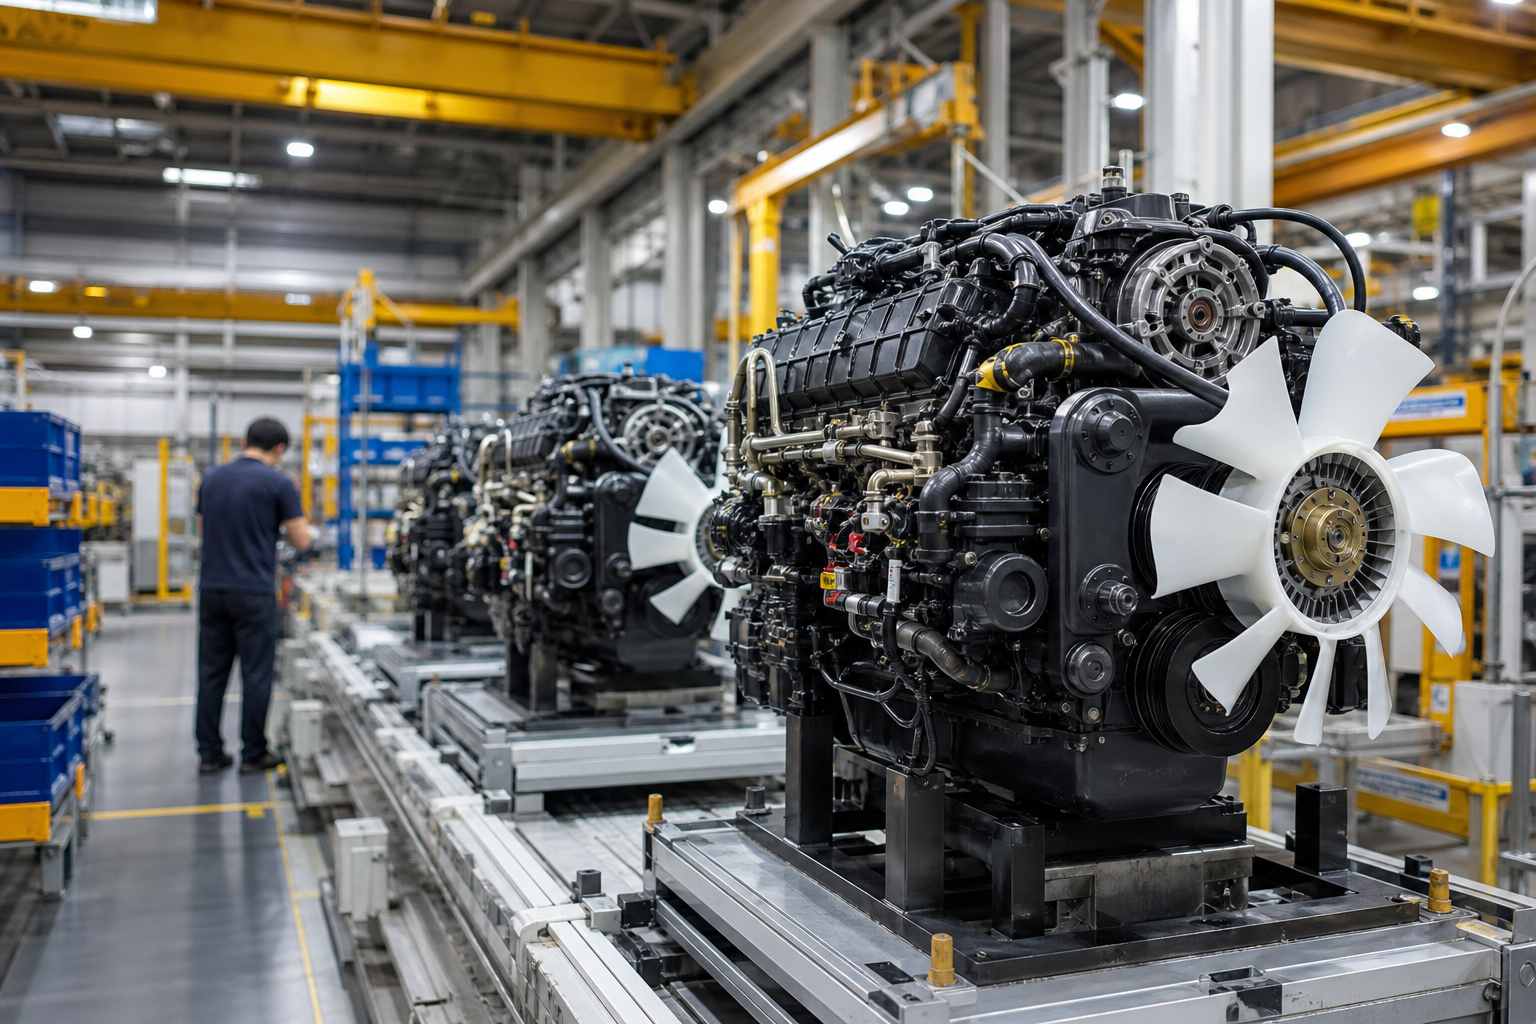
The key driver behind the upgrade is improved business stability from the merger. HD Construction Equipment added an engine business to its existing excavator and wheel loader operations. The engine unit has posted an average operating margin of 12.5% over the past three years, helping offset earnings volatility in the construction equipment segment. The company has solidified its No. 1 position in Korea and achieved a 2.3% global market share on a combined basis in 2025.
The addition of the engine business has translated into stronger profitability. Demand for power generation and defense engines remained solid this year, while construction equipment sales recovered steadily in advanced markets. As a result, the cumulative operating margin for the first three quarters of 2026 rose to 8.7% from 6.0% a year earlier.
Financial soundness also improved on stronger cash generation and debt reduction. The ratio of net debt to earnings before interest, taxes, depreciation and amortization (EBITDA) fell sharply to 0.9 times as of end-June from 3.3 times in 2021. The company plans to raise the share of in-house engines in its construction equipment to 70–80% or higher by 2030 to maximize cost competitiveness and integration synergies.
However, the external environment for construction equipment remains challenging. Prolonged high interest rates in the United States and other major economies have dampened infrastructure investment and increased financing burdens. The won's strength since the second half, logistics delays in the Middle East and diesel supply disruptions in Africa are also weighing on profitability.
HD Construction Equipment is seeking a breakthrough by expanding its high-margin engine business. Last month, it signed a 387.9 billion won (about $286 million) contract with U.S.-based Enchanted Rock to supply gas power generation engines. The expansion of engine plants in Gunsan, North Jeolla Province, and Incheon is expected to further boost the engine unit's contribution to company-wide earnings.
With large-scale spending planned for new integrated platform models and additional capital expenditure, the engine business's ability to generate stable earnings and absorb increased working capital and investment burdens after the merger will determine the pace of mid- to long-term financial improvement.
(Dollar figures are approximate, converted automatically at 1,000 won = $0.738, the rate on Nov. 9, 2026.)
※ This article is an AI translation of the Korean original published by Korea Credit News; it was checked by automated quality guards and published by the English edition desk.