- Published 2026.11.02 10:44
Bottom 20% by assets used 45.3% of credit loans for living expenses
Unlike high-income groups, debt concentrated in daily consumption rather than investment
Welfare-centered debt restructuring needed instead of simply expanding lending
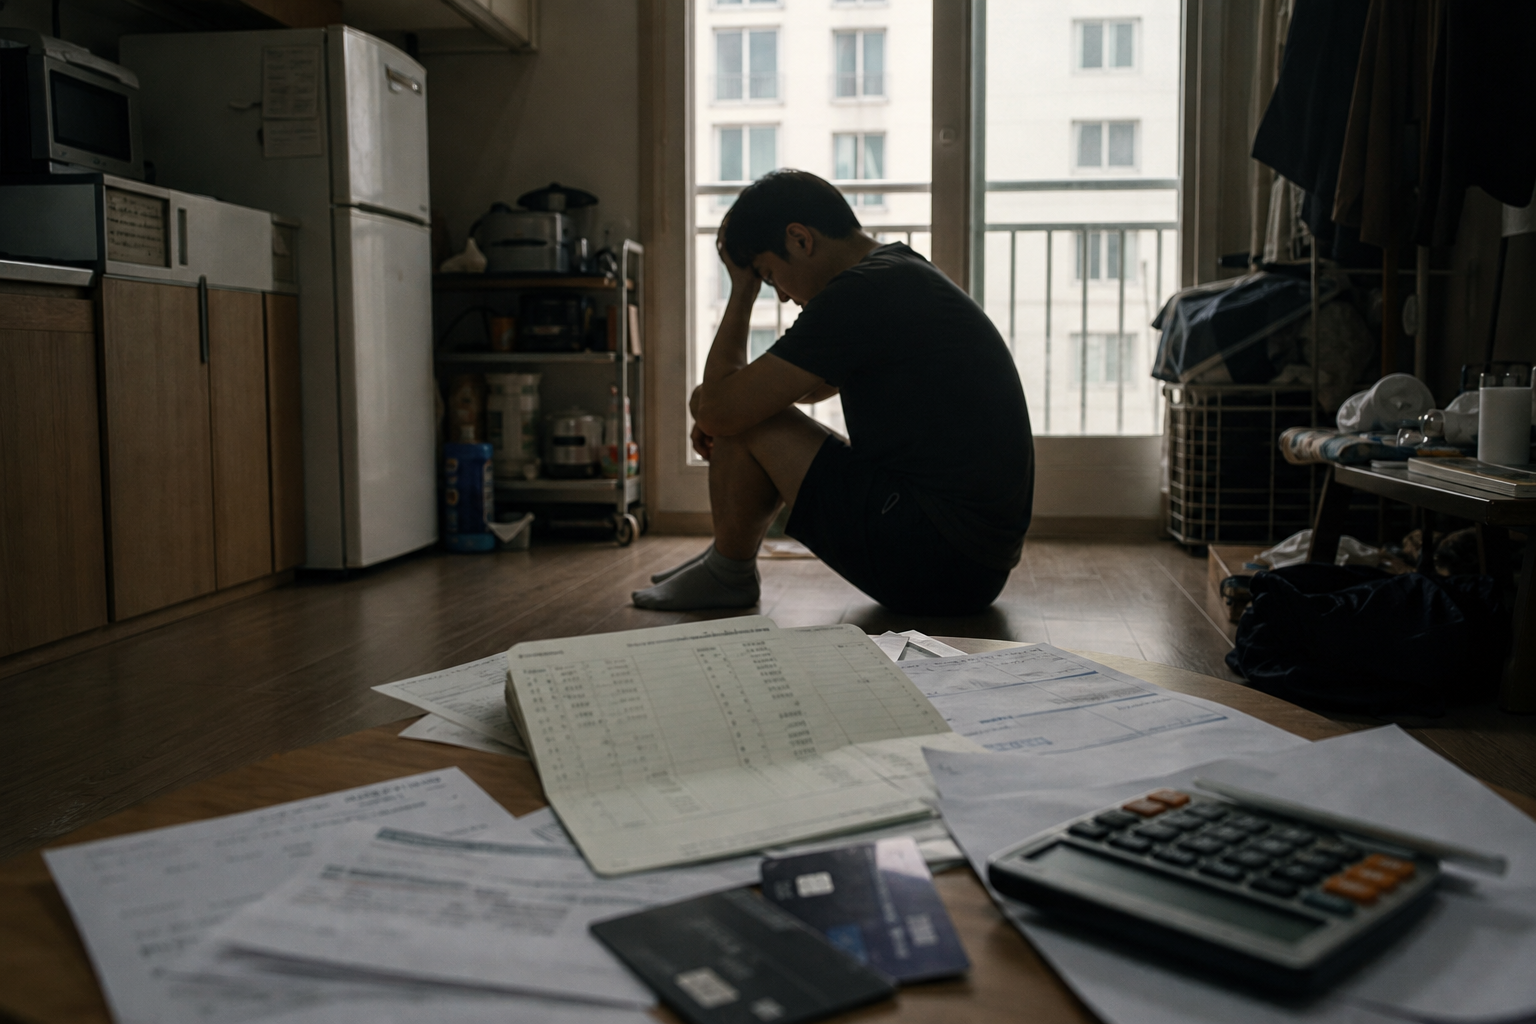
The lowest asset and income brackets have reached a structural limit, relying on high-interest credit loans to cover day-to-day living costs. Borrowers with no collateral and exhausted income capacity are being pushed into the credit loan market, and consumption-driven debt that generates no future value is rapidly becoming a potential default time bomb for financial institutions.
According to credit loan purpose data from the Survey of Household Finances and Living Conditions on KOSIS (Korean Statistical Information Service) on Nov. 2, living expenses accounted for 45.3% of credit loans taken out by households in the bottom 20% by assets last year. That is the highest level since the statistics began in 2017.
The share of living expenses in credit loans for the bottom asset quintile rose from 33.4% in 2017 to 41.9% in 2021, breaking the 40% mark for the first time, and has continued to climb every year since. The bottom 20% by income shows the same pattern. The share of livelihood credit loans for the bottom income quintile jumped from 34.5% in 2024 to 38.2% last year, hitting a record high.
The gap with upper brackets goes beyond a simple difference and clearly shows a qualitative distortion in financial soundness. The fourth and fifth asset quintiles cited business funding and purchases of real estate other than housing as the biggest purposes of credit loans. Credit loans for high-income, high-asset households have the potential to lead to greater repayment capacity through investment, asset growth or business expansion.
In contrast, the bottom asset quintile saw the share of business funding shrink to 19.9% while living expenses approached half. These households are using unsecured, high-interest loans to cover daily consumption such as food, utility bills and medical expenses, let alone build assets.
Unlike secured loans, credit loans have no collateral, so financial institutions bear the borrower's credit risk directly. As a result, interest rates are set higher, and interest burdens surge first when market rates rise or credit risk premiums are added.
In particular, borrowers in the bottom quintile by assets and income have weak repayment capacity, so delinquency and default rates are statistically higher. The interest rates they pay inevitably far exceed market averages, and they face a vicious cycle of multiple debts, taking out more high-interest loans to repay existing high-interest debt.
Looking at past trends, these warning signs have been accumulating. The share of debt repayment as a purpose for credit loans in the bottom asset quintile jumped 6.1 percentage points from 10.1% in 2024 to 16.2% last year. That means more than six out of 10 households are rolling over existing debt with new credit loans while also financing living expenses. It shows that the normal household credit flow of gradually repaying principal and interest through income growth has completely broken down.
The government and policy financial institutions have rolled out expanded policy lending for low-income borrowers and debt restructuring support, but these have clear limits as fundamental measures to curb defaults. Opening up larger loan limits or providing guarantees to low-income, low-asset borrowers is little more than a stopgap that leaves borrowers buried in debt.
Loan support without income backing risks only increasing the absolute size of bad debt through maturity extensions and refinancing loans. There are concerns about a chain of dropouts in which vulnerable borrowers who hit the limit in the mainstream financial system fall into the trap of multiple debts and are pushed to non-bank lenders, private lending businesses and ultimately illegal private lending.
Financial companies will also find it hard to avoid the burden of setting aside provisions for credit loan assets with a high share of vulnerable borrowers. Rather than relying on simply maintaining loan supply or expanding guarantees, there is a growing need to shift policy toward separating the livelihood deficits of vulnerable groups from financial debt and moving them into the fiscal welfare sphere early, while implementing preemptive debt restructuring for marginal borrowers.
Whether second-half policy lending for low-income borrowers shifts its focus from simple liquidity provision to actual debt reduction and fiscal support will be a key indicator for future delinquency rate management in the financial sector. How effectively the inflow of vulnerable borrowers who have lost repayment capacity into the illegal private lending market is blocked also remains an important task.
※ This article is an AI translation of the Korean original published by Korea Credit News; it was checked by automated quality guards and published by the English edition desk.